
Last updated: June 2026 | Reading time: 12 min
Disclaimer: This article is for informational and educational purposes only. Nothing here constitutes financial advice. Tax laws are subject to change and vary by individual circumstance. Always consult a qualified tax advisor or financial planner before making investment decisions.
The thief nobody watches for
There’s a common mistake among investors: they spend hours deciding which ETF to buy and zero minutes deciding where to hold it. That oversight has a price. In a taxable brokerage account, every dividend payment, every capital gains distribution, and every sale is a taxable event. Repeated over decades, that steady drip — poor asset location, or holding the wrong fund in the wrong account — can cost tens of thousands of dollars in taxes that compound against you with the same discipline that interest compounds in your favor.
The good news is that ETFs are already, by design, among the most tax-efficient investment vehicles available to individual investors, well ahead of mutual funds. But not every ETF is equally efficient in this regard. Understanding what drives that efficiency — and which funds stand out specifically for a taxable account — is one of the highest-impact decisions you can make as an investor.
This guide covers how ETF tax efficiency works, what makes some funds dramatically better than others for taxable accounts, and which specific ETFs belong at the top of your list if you are investing outside of a retirement account.
Why ETFs dodge a problem that haunts mutual funds
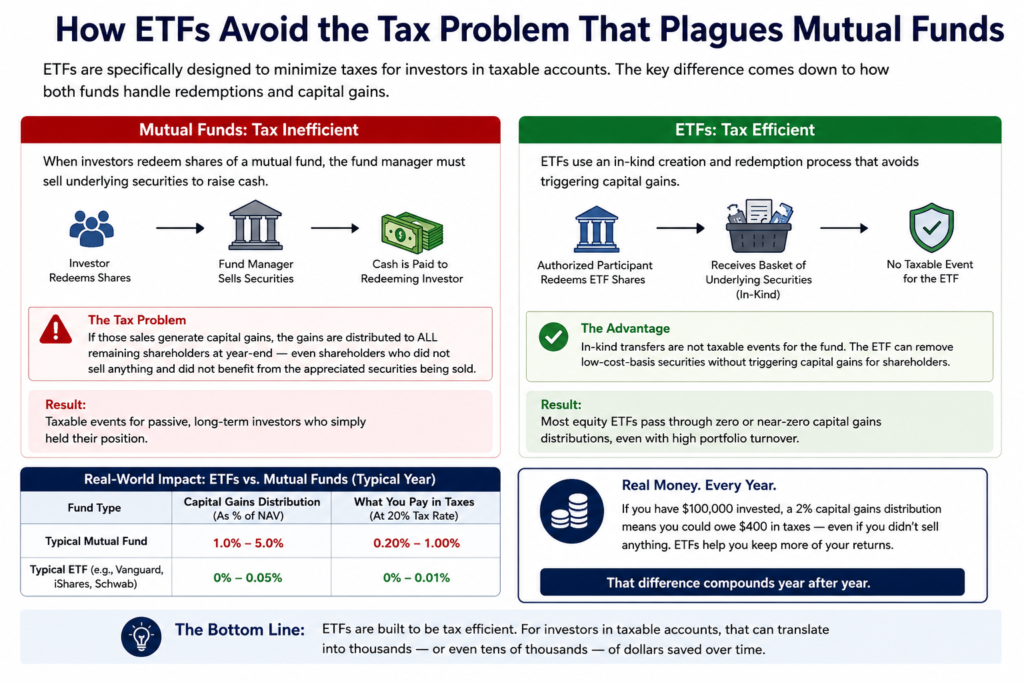
To understand the ETF’s advantage, it helps to look first at the mutual fund’s problem. When an investor redeems mutual fund shares, the fund manager has to sell underlying holdings to raise cash. If those sales generate gains, those gains get distributed to every remaining shareholder at year-end — including people who sold nothing and got none of the benefit from that appreciation. In other words: you pay taxes for decisions someone else made.
ETFs sidestep this through the in-kind creation and redemption mechanism. When an authorized participant — typically a large institution — wants to redeem ETF shares, it doesn’t receive cash. It receives a basket of the underlying securities. That in-kind transfer isn’t a taxable event for the fund, which lets it flush out low-cost-basis positions without distributing gains to shareholders. The result: most equity ETFs distribute zero or near-zero capital gains year after year, even with meaningful portfolio turnover.
That’s why Vanguard, iShares, and Schwab ETFs routinely report zero capital gains distributions while comparable mutual funds hand out gains that can amount to several percentage points of NAV in a single year. For a taxable account investor, that difference is real money staying in your pocket.
The four variables that decide how tax-efficient an ETF really is
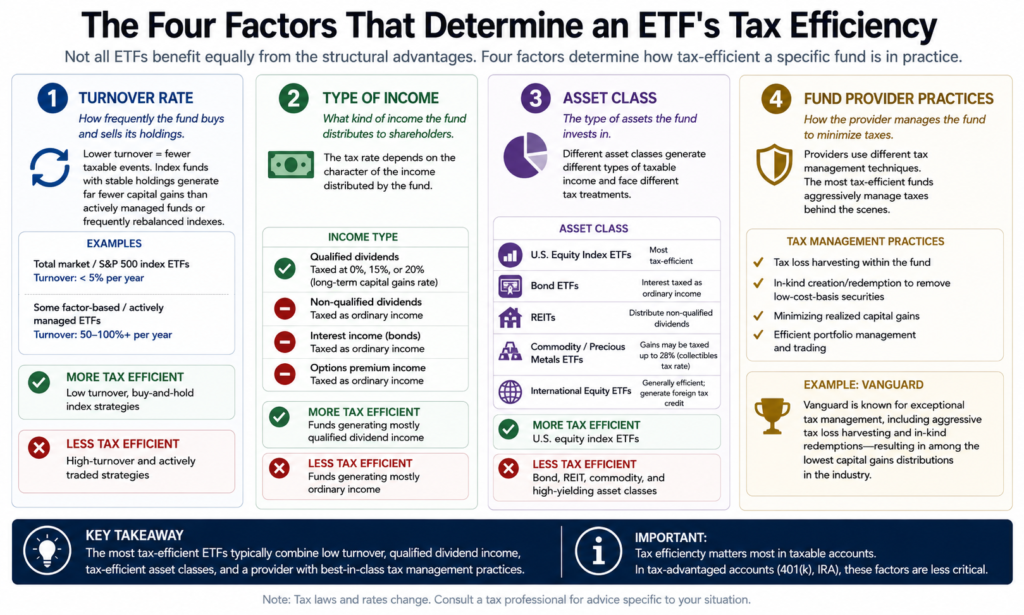
Not every ETF captures this structural advantage equally. Four factors make the difference.
Turnover rate. A fund tracking a stable index with infrequent reconstitutions generates far fewer taxable events than an actively managed fund or one tracking an index that changes composition often. Total market and S&P 500 index funds typically turn over under 5% a year. Some factor-based or actively managed ETFs turn over 50%, 100%, or more, multiplying the chances of taxable gains even within the ETF structure.
Type of income distributed. Qualified dividends — paid by most U.S. corporations and many foreign companies, provided the required holding period is met — are taxed at the preferential long-term capital gains rate: 0%, 15%, or 20% depending on income level. Non-qualified dividends, bond interest, and options premium income are taxed as ordinary income at your marginal rate, which can be considerably higher. A fund that distributes mostly qualified income is, by definition, more efficient.
Asset class. U.S. equity index ETFs tend to be the most tax-efficient. Bond ETFs distribute interest taxed as ordinary income, making them a poor fit for taxable accounts. REITs distribute most of their income as non-qualified dividends. Commodity and precious-metals ETFs can trigger «collectibles» tax rates of up to 28% on gains. International equity ETFs are generally efficient too, with the wrinkle that they generate a foreign tax credit that adds a layer of complexity — and, as we’ll see, opportunity.
The provider’s management practices. Vanguard has historically been particularly aggressive about tax-loss harvesting inside its own funds and using the in-kind redemption mechanism to shed low-cost-basis positions. It’s one reason its ETFs have an exceptional long-term track record of minimal capital gains distributions.
The Best Tax-Efficient ETFs for a Taxable Account in 2026
VTI — Vanguard Total Stock Market ETF
Expense Ratio: 0.03% · Turnover: ~3% · Income Type: Qualified dividends · AUM: ~$450 billion
VTI is the single most tax-efficient large fund available to retail investors and the default recommendation for the core equity position in any taxable account. It tracks the CRSP US Total Market Index, holding over 3,700 U.S. stocks across every market cap from mega-cap to micro-cap. The turnover rate is approximately 3% per year — one of the lowest of any broad market fund — and the fund has distributed zero capital gains in most years of its existence.
The dividends VTI distributes are predominantly qualified, taxed at the preferential rate rather than ordinary income rates. The 0.03% expense ratio is effectively as low as fees go in the ETF industry. There is genuinely no cheaper, more tax-efficient way to own the entire U.S. equity market.
An important structural note: Vanguard’s ETFs and their equivalent mutual fund share classes share the same underlying portfolio, which allows Vanguard to use the ETF’s in-kind redemption mechanism to benefit the mutual fund shareholders as well. This patent expired in 2023, and several other fund providers are exploring similar structures — but for now, Vanguard’s tax management practices remain industry-leading.
VOO — Vanguard S&P 500 ETF
Expense ratio: 0.03% · Turnover: ~2% · Income type: qualified dividends · AUM: ~$550 billion
VOO tracks the S&P 500 and shares almost every tax-efficiency feature with VTI. Its turnover is even slightly lower, partly because the S&P 500 gets reconstituted less often than the total market index. In after-tax returns, the two funds are practically indistinguishable.
The choice between VOO and VTI for a long-term taxable account investor comes down to one question: do you want small- and mid-cap exposure alongside large-caps? VTI includes it; VOO doesn’t. That extra diversification tends to give VTI a slight long-run edge over VOO — though for most investors, either fund is an excellent pick.
VXUS — Vanguard Total International Stock ETF
Expense ratio: 0.07% · Turnover: ~4% · Income type: mixed dividends · AUM: ~$80 billion
VXUS provides exposure to more than 8,000 international stocks across developed and emerging markets outside the U.S. It’s the natural complement to VTI for anyone building a globally diversified equity position in a taxable account.
Here’s a nuance many investors miss: international ETFs generate a foreign tax credit that partially offsets taxes withheld by foreign governments on dividend payments. That credit is only available if the fund is held in a taxable account — it’s lost if the same fund sits in an IRA or another tax-advantaged account. That creates a counterintuitive asset-location argument: for someone who holds both a taxable account and a tax-advantaged one, there’s a real case for keeping international equity specifically in the taxable account, so as not to forfeit that credit.
VXUS dividends are a mix of qualified and non-qualified, with the qualified portion getting the preferential rate. Its long-term capital gains distribution history is minimal, consistent with Vanguard’s broader tax-management philosophy.
ITOT — iShares Core S&P Total U.S. Stock Market ETF
Expense ratio: 0.03% · Turnover: ~3% · Income type: qualified dividends · AUM: ~$60 billion
ITOT is iShares’ take on the same concept as VTI: a total U.S. market fund at the same 0.03% expense ratio with comparable tax efficiency. It tracks a slightly different index (the S&P Total Market Index versus VTI’s CRSP index), producing small differences in the holdings list, but for practical purposes the two funds are interchangeable.
Its real value shows up in tax-loss harvesting. When VTI drops in price, you can sell it, immediately buy ITOT, and claim the loss — keeping nearly identical market exposure while resetting your cost basis. Because the two funds track different indexes, this doesn’t trigger the wash-sale rule. It works the other way too: sell ITOT at a loss, buy VTI. It’s one of the most commonly used swaps in systematic portfolio management.
SCHB — Schwab U.S. Broad Market ETF
Expense ratio: 0.03% · Turnover: ~3% · Income type: qualified dividends · AUM: ~$28 billion
SCHB is Schwab’s version of the same idea: total U.S. market exposure, the same 0.03% fee, comparable tax efficiency. It tracks the Dow Jones U.S. Broad Stock Market Index and holds around 2,500 stocks — fewer than VTI’s 3,700+, but covering essentially the same large- and mid-cap universe.
It’s the third leg of the tax-loss harvesting trio alongside VTI and ITOT. Rotating among all three lets you maintain nearly identical market exposure while harvesting losses across three different index methodologies without wash-sale concerns. For Schwab investors looking to avoid transaction costs, SCHB is the natural core holding, with VTI and ITOT available as swap partners.
QQQ and QQQM — Invesco Nasdaq-100 ETFs
Expense ratio: QQQ 0.20% / QQQM 0.15% · Turnover: ~8% · Income type: qualified dividends · AUM: QQQ ~$290 billion / QQQM ~$40 billion
QQQ and its cheaper sibling QQQM track the Nasdaq-100: the 100 largest non-financial companies listed on the Nasdaq, a portfolio dominated by technology, communication services, and consumer discretionary names. Both are tax-efficient in the sense that they distribute mostly qualified dividends and rarely distribute capital gains, though their higher turnover compared to total market funds reflects more frequent index reconstitutions.
For a long-term individual investor, QQQM is the better pick between the two: it’s structurally identical to QQQ but charges 0.15% versus 0.20%. QQQ mainly exists because it launched earlier and built up massive institutional trading volume, making it the preferred vehicle for institutions and traders who prioritize liquidity over cost. For building a long-term position, QQQM’s lower fee is the obvious choice.
Neither fund matches VTI or VOO’s efficiency given the higher fee and turnover, but both remain far more efficient than a mutual fund or actively managed fund with similar large-cap tech exposure.
ETFs worth handling with care in a taxable account
Knowing what to avoid in a taxable account matters as much as knowing what to favor. Several categories of ETFs that work perfectly well in tax-advantaged accounts create real tax drag when held in a taxable brokerage account instead.
Bond ETFs distribute monthly interest that’s taxed as ordinary income at your marginal rate — potentially 32%, 35%, or even 37% for higher earners. Funds like BND, AGG, or TLT are excellent choices in a traditional or Roth IRA, where that income is either deferred or exempt, but they fit poorly in taxable. If you need fixed-income exposure in a taxable account, I Bonds (for inflation protection) or municipal bond ETFs (whose interest is exempt from federal tax) are more efficient alternatives.
REIT ETFs like VNQ distribute most of their income as non-qualified dividends — ordinary income rather than preferential dividend income — because REITs are required by law to distribute at least 90% of their taxable income. Holding VNQ in taxable means paying your marginal rate on most distributions. REITs belong in tax-advantaged accounts, where that ordinary-income treatment gets neutralized.
High-yield dividend ETFs — JEPI, JEPQ, DVY, among others — generate substantial income that’s taxed every year, and in the case of JEPI and JEPQ, a meaningful portion of that income may be classified as non-qualified. These work well in an IRA; in taxable, the annual tax drag on their high distributions is a real cost.
Actively managed or factor-based ETFs with high turnover — some smart-beta, momentum, or tactical allocation funds — can generate unexpected capital gains distributions even within the ETF structure if turnover runs high enough that the in-kind redemption mechanism can’t absorb it all. Always check a fund’s capital gains distribution history before adding it to a taxable account.
Tax-efficient ETF comparison table
| ETF | Expense Ratio | Turnover | Income Type | Taxable Account Fit |
|---|---|---|---|---|
| VTI | 0.03% | ~3% | Qualified dividends | ⭐⭐⭐⭐⭐ Excellent |
| VOO | 0.03% | ~2% | Qualified dividends | ⭐⭐⭐⭐⭐ Excellent |
| VXUS | 0.07% | ~4% | Mixed (+ foreign tax credit) | ⭐⭐⭐⭐⭐ Excellent |
| ITOT | 0.03% | ~3% | Qualified dividends | ⭐⭐⭐⭐⭐ Excellent |
| SCHB | 0.03% | ~3% | Qualified dividends | ⭐⭐⭐⭐⭐ Excellent |
| QQQM | 0.15% | ~8% | Qualified dividends | ⭐⭐⭐⭐ Good |
| SCHD | 0.06% | ~25% | Qualified dividends | ⭐⭐⭐ Moderate |
| BND | 0.03% | ~60% | Ordinary income (interest) | ⭐ Poor — better in an IRA |
| VNQ | 0.12% | ~8% | Mostly non-qualified | ⭐ Poor — better in an IRA |
| JEPI | 0.35% | ~200%+ | Mostly non-qualified | ⭐ Poor — better in an IRA |
The Tax-Loss Harvesting Pairs Every Investor Should Know
Tax-loss harvesting is the practice of selling an investment that has declined in value, claiming the capital loss on your tax return to offset gains or reduce ordinary income, and immediately reinvesting in a similar — but not identical — fund to maintain market exposure. (If you want a step-by-step breakdown of the mechanics, limits, and wash-sale rules, see our complete 2026 guide on how tax-loss harvesting works with ETFs). The wash-sale rule prohibits claiming a loss if you buy the «substantially identical» security within 30 days before or after the sale, but ETFs tracking different indexes are generally not considered substantially identical even when their performance is nearly identical.
These are the most commonly used swap pairs for taxable account investors:
| If you hold | Swap to | Why it works |
|---|---|---|
| VTI (CRSP Total Market) | ITOT or SCHB | Different index, near-identical exposure |
| VOO (S&P 500) | IVV or SPLG | Same index, different provider — check IRS guidance |
| VXUS (Total International) | IXUS or SCHI | Different index, similar international exposure |
| QQQ (Nasdaq-100) | QQQM or XLK | QQQM tracks the same index — use XLK for wash-sale safety |
| SCHD (Dividend quality) | VYM or DGRO | Different index methodology, similar dividend exposure |
A word of caution on VOO, IVV, and SPLG: all three track the S&P 500. There’s genuine ambiguity about whether the IRS would treat these as substantially identical, since they replicate the exact same index under different providers. Many tax professionals recommend adding a waiting period or swapping into a fund tracking a different but correlated index instead — say, VOO into VTI rather than IVV — to stay on the safe side. Talk to a tax advisor about your specific situation.
Asset location: which ETF belongs in which account
Investing tax-efficiently isn’t just about picking the right funds — it’s also about putting them in the right account. The general rule is simple: tax-inefficient assets (those generating ordinary income or frequent gains) go in tax-advantaged accounts, and tax-efficient assets (qualified dividends, minimal distributions) go in the taxable account.
| Asset Type | Best Account | Why |
|---|---|---|
| U.S. equity index ETFs (VTI, VOO) | Taxable or Roth IRA | Already highly efficient; long-term gains get favorable treatment |
| International equity ETFs (VXUS) | Taxable (to claim the foreign tax credit) | The credit is only available in a taxable account |
| Bond ETFs (BND, AGG, TLT) | Traditional IRA or 401(k) | Interest taxed as ordinary income; better to defer it |
| REIT ETFs (VNQ) | Roth IRA | High non-qualified distributions; best fully sheltered |
| High-yield dividend ETFs (JEPI, JEPQ) | Roth IRA or traditional IRA | Non-qualified income and high turnover; shelter it right away |
| Bitcoin ETFs (IBIT, FBTC) | Roth IRA | Volatile, high-growth asset; maximize tax-free compounding |
| Thematic / sector ETFs (ARKK, BOTZ) | Roth IRA or traditional IRA | High turnover and potential capital gains distributions |
A practical example: building a tax-efficient taxable portfolio
To make this concrete, picture an investor with both a taxable brokerage account and a Roth IRA, holding a globally diversified portfolio across both. A tax-efficient setup might look like this:
In the taxable account: VTI as the core U.S. equity holding, VXUS for international exposure (to capture that foreign tax credit), and QQQM as a satellite growth position. No bonds, no REITs, no high-yield dividend ETFs. The entire taxable account generates mostly qualified dividend income, minimal capital gains distributions, and full access to tax-loss harvesting using ITOT and SCHB as swap partners for VTI.
In the Roth IRA: BND or AGG for the bond allocation, VNQ for REIT exposure, and JEPI for income generation. Every tax-inefficient asset is sheltered permanently, and any growth inside the Roth IRA — from aggressive positions like a Bitcoin ETF to a thematic sector fund — is never taxed on withdrawal.
None of this is complicated to set up. The real discipline is resisting the urge to hold high-yield, income-generating funds in the taxable account because they «look» attractive, when the after-tax return on those same funds inside a Roth IRA is meaningfully higher.
The bottom line
Tax efficiency in a taxable brokerage account isn’t a minor detail — it’s one of the most direct ways an individual investor can improve after-tax returns without taking on a single extra ounce of market risk. The most tax-efficient ETFs for most taxable accounts are VTI, VOO, VXUS, ITOT, and SCHB — broad, cheap index funds that generate qualified dividends, minimal capital gains, and even double as tax-loss harvesting partners for each other.
The funds worth keeping out of a taxable account — bonds, REITs, high-yield covered-call funds like JEPI — aren’t bad investments. They simply belong in tax-advantaged accounts, where their income characteristics work for you instead of against you. Getting that placement right, paired with systematic tax-loss harvesting in the taxable account, is the kind of foundational portfolio hygiene that, sustained over decades of investing, makes a real difference.
Frequently asked questions
What makes an ETF tax-efficient? Mainly three things: low portfolio turnover (fewer taxable events from buying and selling), the in-kind creation and redemption mechanism that lets the fund shed gains without distributing them, and generating qualified dividend income rather than ordinary income. Broad U.S. equity ETFs from Vanguard, iShares, and Schwab score well on all three.
Are ETFs always more tax-efficient than mutual funds? Structurally, yes, for the reasons above — but the advantage varies by fund type. A broad index ETF is dramatically more efficient than an actively managed mutual fund with high turnover. An index ETF and its equivalent mutual fund share class (as Vanguard offers) are more comparable, since both benefit from that shared structure. For most categories, the ETF wins, but the gap isn’t always as large as ETF advocates suggest.
Can I hold SCHD in a taxable account? Its dividends are mostly qualified, which makes it more efficient than a bond or REIT ETF. That said, its roughly 25% annual turnover — driven by its quality screening and reconstitution process — runs higher than total market index funds. It’s a reasonable taxable account holding for someone specifically targeting dividend income, though less efficient than VTI or VOO for someone prioritizing total return.
How much can tax-loss harvesting actually save? It depends on your tax bracket, portfolio size, and market volatility. In a significant downturn — like 2022, when VTI fell roughly 20% — an investor with a $500,000 taxable portfolio could potentially harvest $100,000 in losses, which at a 20% long-term capital gains rate works out to $20,000 in tax savings. Sustained systematically over a multi-decade investing career, that adds up to a meaningful improvement in after-tax returns.
Should I put my most aggressive investments in a Roth IRA? Generally, yes. The Roth IRA’s tax-free growth is most valuable for assets with the highest return potential — volatile growth positions, thematic ETFs, and Bitcoin ETFs all make sense in a Roth IRA if you have the contribution room and a long time horizon. The logic is straightforward: a 10x return inside a Roth IRA is never taxed; the same 10x return in a taxable account triggers a capital gains bill that can eat up a meaningful chunk of the gain.